"Ryan is a skilled mediator who brings neuropsych research and a strong human presence to his work. His preparation process was unique and led to a more successful experience than with other mediators. I was grateful for his non-judgmental stance and ability to reflect what he was hearing and observing."
Co-founder mediation · on video, anywhere
You can’t be in a room with your co-founder. The company still has to ship.
Fifteen minutes, free. Ask me the hard ones:
- How does the three-step process work?
- What happens to our equity?
- What does it cost?
- Can we do this before lawyers?
- Something else?
Tap one to text it to me.
One of you needs out, or both of you do. There’s equity on the table and payroll still runs Friday. $1,995 per founder. One three-hour session on video, usually within a week.
One neutral for both founders. Booking commits you to nothing.
4.9 stars · 282 Google reviews · St. Paul, on video anywhere
“His preparation process was unique and led to a more successful experience than with other mediators.”
Co-founders say they want fairness. What I usually find is that what they actually need is for someone to acknowledge what they put into this — the years, the risk, the thing they gave up to be here. Equity is the surface. Recognition is the thing underneath it.
— Ryan McLaughlin, Flannel People Mediation
The deal you're fighting over was probably made in a day
Co-founder conflict isn't evidence you chose badly. It's structural, it's the most common way companies die, and it starts with a decision almost nobody made carefully.
of ventures concluded the founder equity negotiation in one day or less — at peak uncertainty about strategy, roles, and who would actually still be there in three years.
Hellmann & Wasserman, The First Deal: The Division of Founder Equity in New Ventures (CompStudy survey data)settled the split at or before the founding date — before there was a company with facts to have an opinion about.
Hellmann & Wasserman, The First Deal: The Division of Founder Equity in New Venturesof the startup failures in Wasserman's research trace to people problems inside the founding team — not the product, not the market.
Wasserman, The Founder's Dilemmas, Princeton University PressWhy the equity math never settles it
Founders arrive with a spreadsheet and assume the disagreement is arithmetic. It isn't. Four things are running underneath it, and none of them are solved by a better number.
- It's recognition, not equity. Gottman's work separates solvable problems from gridlocked ones. Gridlock holds when the thing underneath stays unspoken — and for founders that thing is almost always acknowledge what I gave up to be here. Move the number without touching that, and the deal gets signed and resented.
- Reactive devaluation. The identical terms get rated as worse simply because the other founder proposed them — an effect Ross and Stillinger documented at Stanford. It is the clearest reason a neutral has to be the one putting an offer on the table.
- Losses weigh about twice what gains do. Tversky and Kahneman's asymmetry is why a split you'd call fair on a whiteboard still lands as theft on the founder giving something up. Both of you are doing that math, in opposite directions, at the same time.
- "Who sacrificed more" has no floor. That argument cannot be won, because there's no unit to settle it in. The move is to convert it into a question that does have a number: what would it actually cost to replace what each of you put in. One is a grievance. The other is arithmetic.
The session runs on Gottman · Fisher–Ury interest-based negotiation · polyvagal theory · affect labeling
What co-founder mediation actually is
Co-founder mediation is a confidential, voluntary process in which two business partners work out the terms of a split, a buyout, or a reset with a neutral third party — instead of through opposing attorneys. At Flannel People Mediation it runs as a three-step sequence in a fixed order: an individual meeting with each founder, a written intake built around your company, then one three-hour session on video. The fee is a flat $1,995 per founder. Nothing said in mediation can be used in court, and founders leave with the agreed terms in writing.
- Who it's for
- Co-founders and business partners who are splitting, buying each other out, or resetting roles and equity
- Structure
- Three steps, in a fixed order: individual meetings → written intake → one joint session
- Format
- Video. Both founders in the same call, from wherever each of you is
- Session length
- Three hours
- Timeline
- The session is usually available within a week of the intake
- Cost
- $1,995 per founder, flat — $3,990 total for two founders. The initial 15-minute call is free
- Where
- Flannel People Mediation is based in St. Paul, Minnesota. Because every session is on video, founders anywhere in the U.S. or abroad work fine
- What you leave with
- The agreed terms in writing, clear enough for each side's attorney to convert into binding form
- What it is not
- Not legal advice, not arbitration, not a binding ruling. The mediator is neutral and does not represent either founder
- Mediator
- Ryan McLaughlin, Flannel People Mediation — 4.9 stars across 282 Google reviews
You're not just in a business dispute. You're mourning something.
The person you started this with — the one you sent a hundred Slack messages to at midnight, the one who knew exactly what you meant when you said the product wasn't ready — is now someone you're being careful around. Every conversation has a subtext. Every meeting has a side conversation you're not in.
There's equity on paper that neither of you can touch yet. The company is pre-revenue or early-revenue, the shares are nominally worth something, and the fight is about what that future value means and who deserves it. At seed stage, a 50% stake in a $16 million pre-money valuation is $8 million on paper — and zero dollars in anyone's hand. That's what you're negotiating over. And you know it.
The research on what makes co-founder splits so hard isn't really about equity — it's about the "why" conversation. Why it stopped working. Who was right. What should have happened differently. That conversation is a tar pit. You can spend two years and $150,000 in legal fees relitigating it, or you can separate the exit terms from the origin story and move.
There's a window — before attorneys entrench each side in formal positions — where this is still resolvable through conversation. Most founders who find mediation do it after the window closes, when they're already in it. You're reading this page, which means you may still be in the window.
Tell me where things stand. I'll tell you if I can help.
This isn't a lawyer. It isn't arbitration.
Both have their place. Neither one is built for where you are right now.
Hiring a Lawyer to Negotiate
Once attorneys are involved on both sides, positions harden fast. A negotiated departure through lawyers typically runs $5,000–$20,000. If it goes contested — IP disputes, fiduciary claims — you're looking at $100,000–$250,000 per side, and 12 to 27 months. The process is public record. Investors see it.
Arbitration
Arbitration is adjudication with less procedural overhead. Someone still decides for you. The process is adversarial by design. You don't get self-determined terms — you get a ruling. And voluntary compliance with rulings you didn't agree to runs well below 60%.
Co-Founder Mediation
A structured, confidential process where you and your co-founder — together with a neutral — work out the terms yourselves. Nothing said in mediation can be used in court. You leave with a written agreement that both of you actually made. $1,995 per founder — $3,990 for the two of you, start to finish.
It isn't one meeting. It's a sequence, and the order is the point.
Three steps. $1,995 per founder. Each one exists to make the next one possible.
Most mediation takes two people who can barely look at each other, puts them in the same room, and asks them to negotiate. That's backwards. Perspective-taking, weighing options, imagining a future you haven't agreed to yet — all of it runs through the prefrontal cortex. And the prefrontal cortex is exactly what goes quiet when your brain reads the person across from you as a threat. You can't reason your way out of a state you aren't in.
So the sequence doesn't open with negotiation. It opens by getting each of you out of threat, separately, and it doesn't put you in the same call until the call can hold it. The order isn't a scheduling preference. It's the mechanism.
-
An individual meeting with each founder
Separate conversations, before anyone is in the same room. I find out what each of you actually needs — not the stated position, the interest underneath it. What a workable outcome looks like. What you're afraid of. Where there's more flexibility than either of you has admitted out loud.
Why it's first — Naming a feeling precisely and out loud measurably reduces limbic reactivity, and it works on people who are certain it won't (Lieberman et al., Psychological Science, 2007). It's also where procedural justice gets built: parties who believe the process itself is fair accept outcomes they don't love. That belief has to exist before the joint session, because it can't be manufactured during one.
-
A written intake, with questions built for your company
You each complete an intake in writing. After the individual meetings I add questions specific to your situation — the vesting schedule, the IP assignments, who put in cash and who put in sweat, what the operating agreement does and doesn't say about a founder leaving.
Why it's written, and why it's second — Writing about a conflict does something talking about it doesn't: it loosens attribution bias, the reflex that explains your own behavior by circumstance and the other person's by character. Eli Finkel's work at Northwestern is the cleanest demonstration of it. The practical effect is that the three hours we have get spent negotiating — not on me learning your cap table.
-
One three-hour session on video, usually within a week
Three hours, both founders and me. We work the issues a co-founder split almost always turns on: how equity and unvested shares get handled, who owns what IP, what role (if any) the departing founder keeps, non-compete terms, and how the exit gets valued when there's sweat on one side of the table and cash on the other. You leave with the agreed terms in writing — clear enough that each side's attorney can convert it into binding form without relitigating it. Not a legal contract. The deal the two of you made.
Why it's last — By the time you're both on the call, each of you has been heard alone and each of you has put it in writing. That's two passes at bringing the threat response down before anyone has to sit across from anyone. Perspective-taking is available now in a way it was not three weeks ago. That's the entire reason it's third.
Skip the first step and the third one becomes a fight. Skip the second and the third becomes an interview. Run them in order and three hours is enough — which is the only reason I can quote you a flat number instead of an hourly rate and a shrug.
What a realistic resolution looks like
Not a perfect ending. A workable one. Which is usually enough.
Clean exit with agreed terms
One founder leaves. Unvested equity goes back to the company. Vested shares are either retained or repurchased at a price you both agreed to. IP stays with the company. The cap table makes sense. The departing founder is treated with visible respect. Both people can describe what happened the same way. The mediation summary goes to each party's attorney for formalization — that step is shorter when neither side has anything left to argue about.
Business continues — one founder
The company doesn't shut down. The remaining founder has clear authority and a cap table that reflects the new reality. Investors know what happened. Employees don't have to pick sides. The company can still raise, hire, and operate. The window the split opened gets closed.
Equity clarity without litigation
The fight about who deserves what — cash investor vs. sweat equity — gets resolved through conversation, not a judge. Both perspectives are heard. The agreement reflects something closer to what actually happened, not what each side can prove in court. That's a different document.
Confidential — no public record
Nothing said in mediation can be used in litigation later. The process doesn't appear in court records. Your investors don't read about it. What happens in the session stays there — and what you leave with is an agreement, not a deposition.
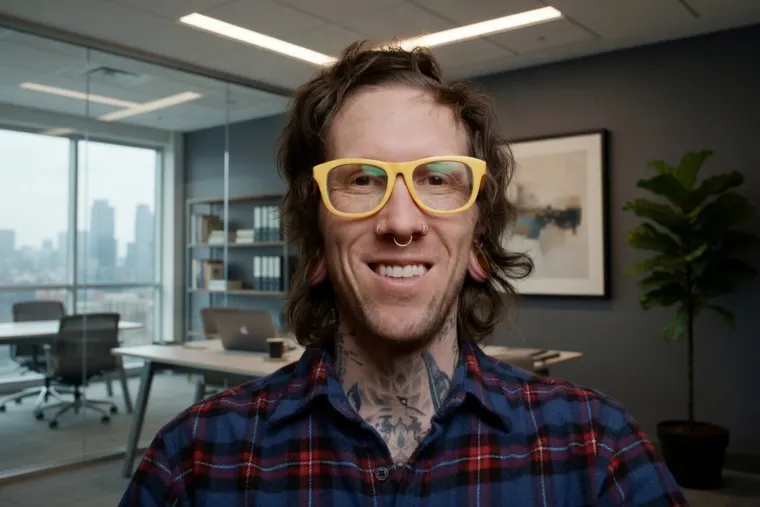
Ryan McLaughlin
Mediator · Flannel People Mediation · St. Paul, MN
I'm not a therapist, not a lawyer, not a business consultant. I'm a mediator — which is a specific thing. My job is to stay in the room while the hard conversation happens, keep it from going sideways, and make sure both people actually get to express what they need rather than performing their negotiating position at each other.
I understand business structures: vesting schedules, operating agreements, the difference between a cap table problem and a communication problem, why the same equity split looks fair to one person and completely wrong to the other. I can engage with the specifics of your situation — I'm not going to need you to explain what a cliff is or why an LLC operating agreement matters. What I don't do is tell you what the terms should be. That's not mediation. That's consulting. Those are different jobs.
The co-founder disputes I've found most useful to work on are the ones where both people still respect each other somewhere underneath the grievance — they're just stuck and they need a structure that lets them say what they actually want without it being interpreted as an opening legal position. 4.9 stars across 282 Google reviews from people who walked in not sure this would work.
Ryan has 4.9 stars across 282 Google reviews.
Here's what the experience is like.
"I was skeptical going into this as I had thought that in all situations you should or needed a lawyer to move forward. I was completely wrong. Ryan guided us through every step and helped with any questions we had."
"Ryan did a great job throughout the mediation process. It took us two sessions to work through everything, but he kept the conversations productive and helped both sides stay focused on finding solutions."
Questions I usually hear on the first call
Order and preparation. A lot of mediation is a single joint session where the mediator meets both of you for the first time in the same room — which means the first hour goes to catching up and the second goes to whoever talks loudest. Here, I've already met each of you alone, and I've already read a written intake with questions I wrote after those meetings. That's two rounds of work before the session starts, and it's why one three-hour block is enough. The sequence is built on the same body of research I use inside the session: affect labeling, procedural justice, and the fact that perspective-taking isn't available to a brain that's reading the other person as a threat.
No, and yes. Flannel People Mediation is based in St. Paul, Minnesota, but every part of this runs on video — the individual meetings, the intake, and the three-hour session. Co-founders in different cities, different states, or different countries are normal. All we need is a time zone overlap wide enough to hold three hours.
Mediation is voluntary — both people have to agree to the process. That said, "I don't want to do mediation" often means "I don't know what I'm agreeing to" or "I'm afraid of what happens if we try this and it doesn't work." The free call is sometimes useful just to understand where the resistance is coming from. Sometimes one founder calling in and explaining what the process actually is — confidential, non-binding, not litigation — changes the other person's read on it.
It matters in that you don't have a written framework to fall back on — no agreed valuation clause, no deadlock mechanism, nothing that says what happens when one of you wants out. That's actually more common than founders assume, especially at the early stage. It doesn't prevent mediation. In some ways it makes mediation more necessary, because there's no document to hand to a lawyer and say "go from here." You need to build the terms from scratch. That's exactly what the process does.
Valuing equity is not my job — that's for accountants, investors, or 409A appraisers, depending on the company's stage. What I can help with is structuring the conversation about how the equity gets treated during a departure: whether unvested shares go back to the company, whether vested shares are retained or repurchased, and at what price and on what timeline. The conversation about value is part of mediation. The actual number is something you may need external help to establish — and I'll tell you that clearly if it comes up.
A lawyer represents you. Their job is to get you the best possible outcome for you — which means their opposing number is doing the same thing for your co-founder. That's useful when you're already in an adversarial position and the relationship is past saving. But it tends to harden positions fast, and once both sides are represented, the cost and timeline escalate quickly. Mediation has a neutral in the room — someone who isn't on anyone's side. The goal is a deal both people actually agree to, not a ruling one side wins. Those produce different kinds of agreements.
Mediation doesn't always produce a full resolution — but it almost always produces clarity. Sometimes both founders leave knowing exactly what the sticking points are, which makes the next conversation — whether that's with lawyers or with a board — a different, shorter conversation. Nothing said in mediation can be used in any subsequent legal proceeding. You're not giving anything up by trying it. And if you end up in litigation anyway, you'll at least know that you tried the shorter path first.
$1,995 per founder — $3,990 for the two of you. That covers the whole process: the individual meeting with each founder, the written intake with questions built for your company, the three-hour session, and the agreed terms in writing. Flat fee, quoted before anything starts. For context: a negotiated departure through separate attorneys typically costs $5,000–$20,000. A contested dispute can reach six figures per side. The initial 15-minute call is free.
Ready? Pick a time below.
Free 15-minute call. No commitment.
The window is still open. For now.
Before attorneys entrench each side in formal positions, there's a period where this is still resolvable through conversation. Most founders who find mediation reach it after that window closes. The free call takes 15 minutes. You'll know within the first five whether this makes sense for your situation.
You're on the calendar.
Check your email for the confirmation. Here's what to think about before we talk:
- Note the key stakeholders — both founders, and whether any investors or board members are involved in the dispute
- Pull together whatever documents you have: operating agreement, cap table, any vesting schedule or equity grant letters
- Think about what a good outcome looks like for you — not your position, but what you actually need from this
- No prep required beyond that. We'll figure out the rest on the call.
Questions before the call? 763-316-8323